Government borrowing is getting more expensive.
Since October, major global bond markets have experienced a severe sell-off, with yields surging dramatically: the US 10-year Treasury yield briefly hit 5.36%, the highest since 2002; the French 10-year yield neared 5%, a 24-year peak; and the UK 30-year gilt yield topped 6%, a level not seen since 1998. But government bond yields in major economies retreated slightly from their peaks on Friday.
According to a Fitch Ratings report published on October 13, the average 10-year government bond yield across the ten largest advanced economies has risen by 81 basis points since 2026. Total government debt in developed markets is projected to increase by $4 trillion by the end of the year, reaching over $75 trillion, with the top ten advanced economies accounting for $68.5 trillion of that total.
What forces are driving up global borrowing costs? Who will be hit hardest in this debt storm? And how will this affect sovereign credit ratings? National Business Daily recently interviewed several economists at Fitch Ratings to unpack these questions.
Surging Global Bond Yields: Government Issuance Meets Tech Giant Borrowing
Discussing the drivers behind the recent yield spike, Brian Coulton, Chief Economist for Fitch Ratings, told NBD, "A large part is related to the shifting outlook for monetary policy as a result of a longer than expected energy shock that has made central banks increasingly nervous about second round effects - and the arrival of a much more hawkish Chair at the Fed."
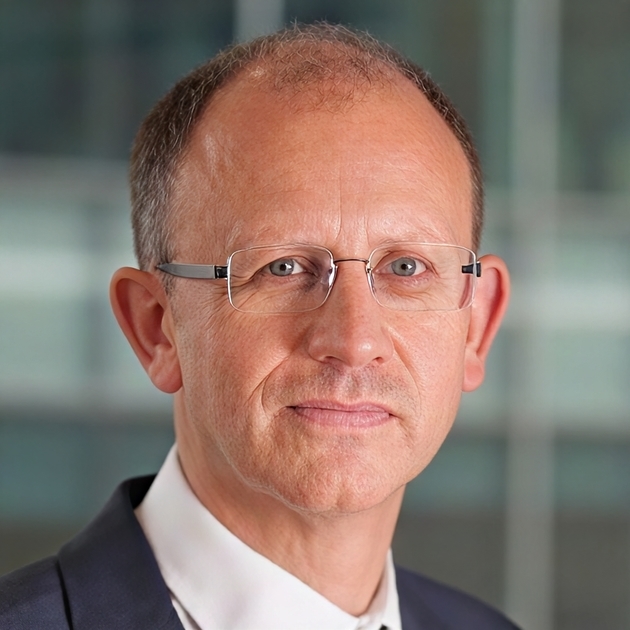
Brian Coulton Photo/website of Fitch Ratings
However, a noteworthy signal is that it's not just short- and medium-term bonds affected by monetary policy that are volatile; ultra-long yields, such as the 30-year, have risen at the very long end, while medium to long-term inflation expectations have not budged. "We think this signals that broader demand and supply factors are also playing a role," Coulton noted.
The first squeeze on the supply side comes from governments' expanding fiscal deficits. To maintain vast public spending and refinance maturing debt, major advanced economies are continuously issuing new debt. On October 13, the International Monetary Fund (IMF) stated in its latest World Economic Outlook that net borrowing by global advanced economies will reach 5.2% of GDP this year, the highest since 2021.
Meanwhile, tech giants are also competing for capital alongside sovereign nations. Coulton pointed out to NBD, "The step up in market borrowing by the hyper-scalers this year to fund the IT capex boom appears to be creating more competition for sovereign borrowers in debt markets."
Goldman Sachs projects that bond issuance by the five major hyperscalers will be around $250 billion in 2026 and reach $400 billion in 2027.
"With investment demand rising and saving not increasing, this is putting upward pressure on US and global real interest rates," Coulton explained.
Advanced Economy Debt Expected to Top $75 Trillion This Year; US, France, and UK Debt Stability Threatened
The Fitch report indicates that average 10-year government bond yields across the ten largest developed economies have risen by 81 basis points so far this year. This increase is expected to add nearly $4 trillion to the total government debt of developed markets, pushing it past $75 trillion. Of this, the total debt of the ten largest advanced economies is projected to reach $68.5 trillion.
According to data from the Institute of International Finance (IIF), even before the latest bond sell-off, advanced economies paid more than $3.3 trillion in interest last year on internationally traded government bonds, exceeding total global defense spending or total AI investment.
Federico Barriga Salazar, Senior Director and Head of Western Europe Sovereigns at Fitch Ratings, told NBD, "Increase in borrowing costs is a significant adverse development for all developed markets, in particular those with high debt levels (France, US and UK) and bulky redemption profiles."
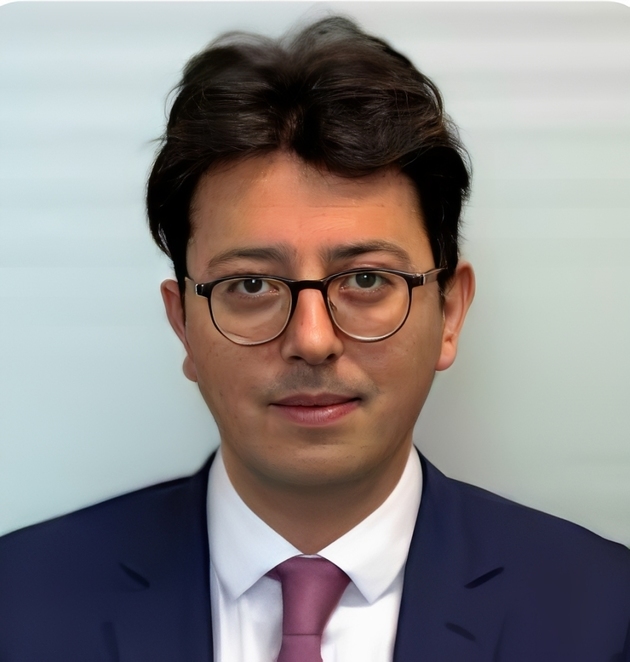
Federico Barriga Salazar Photo/website of Fitch Ratings
IMF Managing Director Kristalina Georgieva recently warned that advanced economies have become the worst offenders when it comes to debt. As government interest payments climb, fiscal space is further squeezed, limiting countries' ability to provide cost-of-living support to citizens.
The "moat" determining whether a country's finances can weather the storm largely depends on the average residual maturity of its outstanding debt. Barriga Salazar stated, "Average maturities of the debt profile can be an important mitigant to absorb higher borrowing costs; the UK in this case has the longest average maturity (13.4 years), followed by France (8.2), meaning interest rate burdens will increase only gradually in those two countries."
However, he also warned, "However, France also has high residual maturity in short term (15.9% of GDP) meaning that changes in financing conditions can still have a short-term effect."
Addressing concerns that volatility in French bond markets might reignite the European debt crisis, Barriga Salazar offered a relatively measured assessment. He emphasized, "Contagion risks were an important factor during the eurozone crisis and highlighted how volatile market conditions can have a detrimental effect on multiple countries; hence the efforts put in place from an institutional point of view—ESM, Banking Union, different ECB support mechanisms—aim to prevent such spill-overs from becoming very disruptive."
Three Deteriorating Indicators Could Trigger Sovereign Rating Downgrades
As debt markets fluctuate, concerns are growing over whether this will impact sovereign credit ratings.
Ed Parker, Managing Director and Global Head of Research for Sovereigns and Supranationals at Fitch Ratings, told NBD, "Higher borrowing costs will worsen budget deficits and make it harder to stabilize or reduce government debt/GDP ratios, other things equal."
The Fitch report highlights that the median 10-year government bond yield for the ten largest advanced economies is 161 basis points higher than the average interest rate on their outstanding debt, making it significantly harder to reduce or even stabilize debt levels.
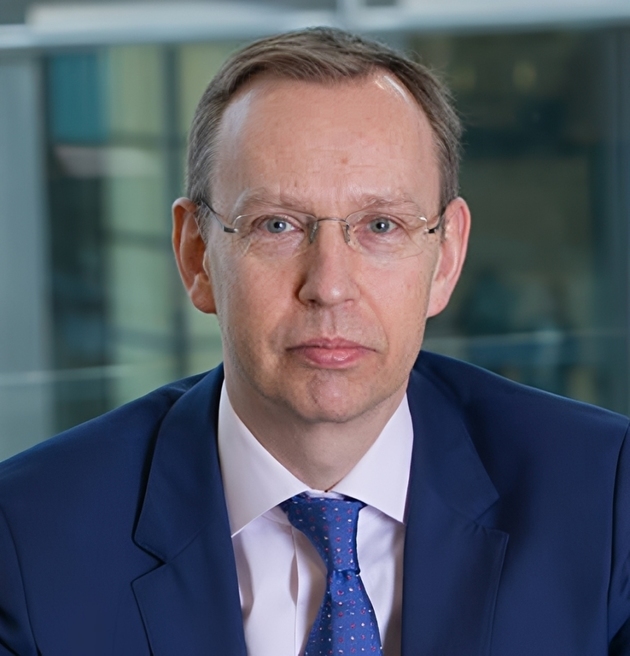
Ed Parker Photo/website of Fitch Ratings
"However, the generally long maturity of government debt means that it takes time for higher bond yields to feed through to the average effective interest rate on the debt stock, providing time for governments to respond," Parker explained. "If such a self-reinforcing cycle emerges then the announcement of a credible medium-term fiscal adjustment plan can be a way of shifting market dynamics." But he warned, "A rapidly rising debt ratio, without a credible fiscal plan or the political capacity to act can indicate increasing risks to public debt sustainability."
Parker pointed out that markets should closely monitor three signals: "Failure to reduce substantial budget deficits, rising interest/revenue ratios and increasing government debt ratios would put downward pressure on some developed market sovereign ratings, particularly in the absence of credible medium-term fiscal consolidation plans and political environments that are unconducive to taking corrective policy action."
Fitch downgraded France's sovereign credit rating in 2023 and 2025 to its current A+. The agency also downgraded the US sovereign rating from AAA to AA+ in 2023. "In both cases, further deterioration in public finances are rating sensitivities," Parker noted.
Taking France as an example, Fitch estimates that to keep its debt burden stable, France must cut its primary fiscal deficit from an expected 2.9% to 0.4% of GDP this year; if actual financing costs rise to current market yield levels, France would need to implement additional fiscal adjustments equivalent to approximately 3.1% of GDP.


 川公网安备 51019002001991号