Recently, AI-related technology stocks across major global markets have experienced sharp volatility, intensifying market concerns over the massive capital expenditures, debt financing, and future profitability of the AI sector.
Has the AI rally come to an end? Has the "AI bubble" begun to burst?
On October 21, Athanasios Vamvakidis, Deputy Director in the Monetary and Capital Markets Department at the International Monetary Fund (IMF), shared key insights during an exclusive interview with National Business Daily (NBD), the fundamentals of current AI investments remain solid, with real demand for computing power and strong profitability among leading enterprises. However, in parts of the market, expectations might be running ahead of realized earnings.
At IMF, Athanasios Vamvakidis oversees Capital Markets, Financial Sector Stability, Payment Systems and Digital Money, and leads the Global Financial Stability Report. After his initial tenure at the IMF, he became Managing Director and Global Head of G10 Foreign Exchange Strategy at Bank of America, where he earned the top ranking for FX strategy in the Institutional Investor Survey for both the US and Europe.
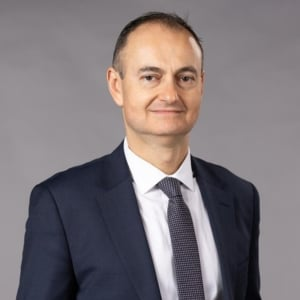
Athanasios Vamvakidis Photo/IMF website
An "AI bubble" may not have formed yet, but expectations might be running ahead of realized earnings in parts of the market
NBD: How strong are the fundamentals behind the current AI investment boom? In your view, which key indicators are most critical for determining whether an AI bubble exists?
Athanasios Vamvakidis: The AI investment boom has stronger foundations than a simple speculative episode. Demand for computing capacity is real, leading firms are profitable, and AI could raise productivity.
But expectations might be running ahead of realized earnings in parts of the market. The most useful indicators are valuations relative to expected profits; the pace and financing of capital spending; concentration in a small group of firms; leverage used by investors; and evidence that AI adoption is translating into revenues and productivity.
The key question is therefore not whether AI is transformative, but whether current prices assume benefits that arrive too quickly or too broadly.
NBD: Are there signs that these investments are producing sufficient revenue?
Athanasios Vamvakidis: So far, earnings keep surprising to the upside. That's why, when you look at valuations, they are not necessarily stretched. Price-to-earnings ratios in some cases have fallen.
The question, however, is: if you look at these companies' investment plans going forward, they are huge. So the market has some questions about whether earnings will actually continue to be strong enough to justify this investment.
It is more of a forward-looking concern, given the huge investment plans these companies have today.
Earnings are strong. And again, although expectations have been very optimistic, earnings keep surprising to the upside.
NBD: Current market discussions about an AI bubble focus mostly on U.S. and South Korean equities. How do you see the AI investment in China's A-share market?
Athanasios Vamvakidis: It's a different cycle, in a way.
Obviously, the U.S. has many companies—the hyperscalers—and in the U.S., the South Korean market has two companies specifically that are driving asset prices.
China has its own cycle, in a way, that follows a different approach. Also because China does not have foreign investors in the same way as in the U.S. and Korea, so it's a completely different case.
But in all these cases, it is hard to argue that valuations are stretched because, again, the sector is developing and earnings are strong.
It's only a matter of whether, looking forward, this optimism will prove to be right or not. This applies to all the economies involved in this AI process.
Simultaneous corrections in AI assets and bond markets could trigger a "perfect storm" for the global financial system
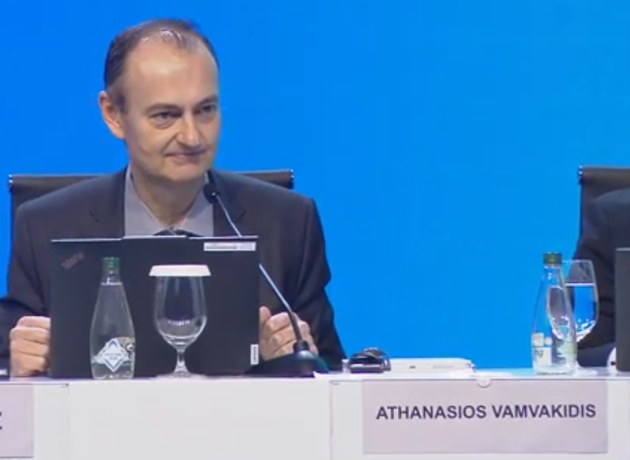
Athanasios Vamvakidis delivering the Global Financial Stability Report. Photo/IMF website
NBD: What is the most critical risk that needs attention in the current AI market?
Athanasios Vamvakidis: The main concern is the very high concentration in AI.
Although, as I said before, valuations are not necessarily stretched and earnings are very strong, market concentration in AI is very high and is increasing. At the same time, wealth effects from strong asset prices in the sector have been supporting the economy.
The concern is that if there is disappointment in AI—either because earnings disappoint, or the very ambitious investment plans do not materialize—it would not only affect asset prices in the sector but also have broader implications.
It would affect the broader market, the real economy, and the global economy, because the rest of the world's ownership of U.S. stocks is at its highest level ever and, to a large extent, is concentrated in AI.
NBD: If an AI market correction coincides with a surge in sovereign bond yields, could they form a negative feedback loop that further amplifies global financial stress?
Athanasios Vamvakidis: Right now, that's actually a very important question in markets, because we have seen an increase in yields caused by the sell-off in the sovereign bond market, and yet risk appetite remains strong.
We have seen some volatility in equities recently, but nothing compared with what we have seen in rates. There is a question: is there a risk that the increase in yields we have seen could trigger an equity-market sell-off?
So far, it has not happened, partly because the increase in yields we have seen is consistent with fundamentals.
But in a scenario in which yields increase further and we see a reduction in risk appetite and an equity-market sell-off, that would be a negative scenario—a very negative scenario—because then you would not have resilience.
We have resilience today because asset prices are strong and risk appetite is strong. If you get an equity-market correction in addition to the bond-market correction we're seeing today, that's a perfect-storm scenario.
NBD: If a systemic crisis really happens, where is the most vulnerable link in the global market?
Athanasios Vamvakidis: We look at a number of vulnerabilities. Recent reports show that the banking sector is resilient based on severe stress tests. There is a tail of weak banks that would be undercapitalized in a severe scenario, including a market correction in AI.
But the vulnerabilities are actually outside the banking sector, and the banks that are most vulnerable are those with links to so-called non-bank financial intermediaries. We have seen increasing leverage and increasing maturity mismatches in the financial sector outside banks—hedge funds, for example.
Banks have been lending to hedge funds, and to a large extent they are exposed to the strong risk appetite we have seen, including in the AI sector. So, in an extreme scenario, if something were to break, it would most likely be outside the banks.
And it's not only hedge funds: we also look at private credit, pension funds, and insurance. Everywhere we see an increase in leverage, which is supporting markets today but could amplify a shock in a negative scenario.
NBD: If the AI market undergoes a sharp correction, through which channels would the risk spill over from tech into other asset classes and the real economy?
Athanasios Vamvakidis: There are two channels.
One is countries that benefit directly from the AI expansion, the investment boom, and strong asset prices. These are the economies that have been doing very well and basically riding this AI wave.
In a negative scenario, these would be the economies affected the most. It is reasonable that those benefiting the most would suffer the most in a negative scenario, and this includes some economies that have been at the frontier of AI development.
So, one question is: to what extent have you benefited from the AI boom, and because of that, how much would a negative scenario affect your economy?
The second channel has to do with risk sentiment, and this is particularly relevant for emerging markets. You may have some emerging markets that are not necessarily involved in the AI ecosystem but benefit from strong risk sentiment.
If you get a bear market or a market correction through a reduction in risk appetite, some emerging markets will also see capital outflows.
And I want to clarify: it's not that everything will necessarily turn negative; AI may work out fine. But the heavy reliance on AI makes the global economy very vulnerable to a negative scenario.
Only by upholding its inflation target can the Fed alleviate pressure in the bond market
NBD: With the Federal Reserve's rate decision approaching, market expectations on rate cuts remain sharply divided. If the Fed keeps rates higher for longer, could global liquidity tightening trigger a sharp correction in U.S. and global assets?
Athanasios Vamvakidis: Actually, what's interesting is that Fed tightening in response to high inflation is not tightening financial conditions. It actually helps control long-term yields, because the Fed's credibility is extremely important in order to avoid a further increase in long-term yields.
To the extent that the Fed is tightening consistently with its mandate to meet its inflation target, this is actually positive for the bond markets. In any case, at the short end of the curve, the market has already priced in these hikes. Therefore, delivering these hikes should not have much of an impact.
On the contrary, failing to respond to inflation pressures will lead to a steepening of the yield curve, and long-term yields will increase.
The best thing the Fed can do to help address the pressures we see today in the bond market is to stick to its inflation target.
NBD: With U.S. government deficits remaining high and debt issuance surging, how high can long-term Treasury yields push global borrowing costs? What is the debt-servicing pressure on highly indebted institutions and emerging markets?
Athanasios Vamvakidis: Actually, what's interesting is that all the fiscal concerns have not triggered the increase in yields that we have seen in the last one or two months. They have contributed, and economies with fiscal imbalances have been more vulnerable.
This includes the U.S., given that the deficit is relatively high. In such cases, high deficits and high yields increase debt-servicing costs, which increase the deficit even further, which then puts pressure back on the bond market.
It's hard to have a specific level in mind, but given how much yields have increased, as debt matures, debt-service costs will keep increasing.
So the best thing that not only the U.S. but also countries with high deficits and high debt levels can do is put together credible fiscal-consolidation plans. By doing so, they can help reduce long-term yields. This will actually help offset any potential impact of fiscal tightening on financial conditions.


 川公网安备 51019002001991号